The calculation sheetGivers and recipients
Gift tax in France: allowances, cash gifts and the declaration
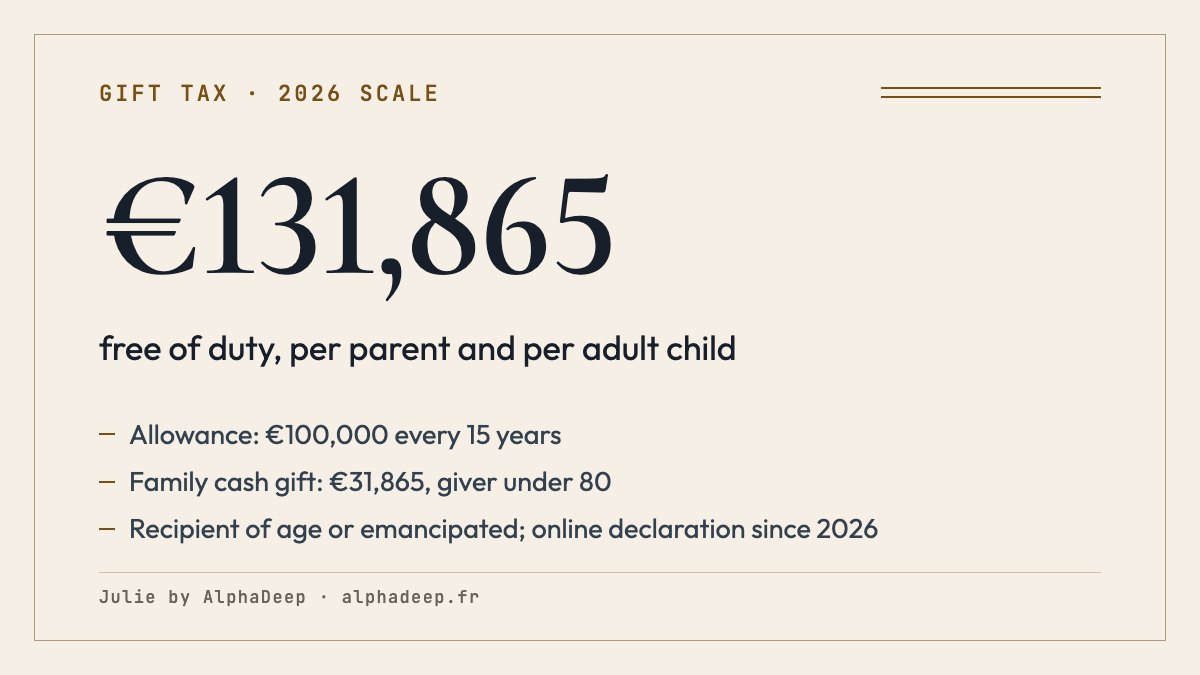
Each parent can give €100,000 to each child free of French gift tax, an allowance renewed every 15 years (General Tax Code, article 779). A family gift of cash adds €31,865 exempt when the giver is under 80 and the child is of age or emancipated (article 790 G). Above that, the scale starts at 5%. Since 2026, a gift of cash or other movable property is declared online.
Go to the tool: the calculation sheet
Julie by AlphaDeep is an AI legal assistant for French law: it researches official references to help answer your questions (Légifrance, case law, service-public), analyses your documents and drafts your letters, for individuals and professionals alike.
General legal information with official references and dated checks. It is not personalised advice: for a decision that commits you, have your situation checked by a qualified professional.

Let’s look at your situation
Give the family link, the amount and any earlier gifts.
Example questions
Your question carries over after signup. Maximum 400 characters. Avoid health data and names.
How much gift tax will you pay on your gift?
Choose the family link, what is given, the amount and both ages: the calculator applies the family cash gift, the allowance left over 15 years, then the scale. The example is a parent aged 62 giving €150,000 in cash to a child aged 30, with no earlier gift.
Fictional example · gift duty
Indicative duty: €1,821.35. Online declaration required since 1 January 2026.
- Family cash gift exempt (€31,865.00 at most)
- €31,865.00
- Allowance used on this gift
- €100,000.00
- Taxable share
- €18,135.00
- Indicative gift duty
- €1,821.35
- Allowance still available on the gift date
- €0.00
Estimate without special reductions and without the temporary exemption for a new home. Allowances apply per giver. Gifts to ascendants or other relatives outside the listed categories, split ownership, representation and international tax treaties need a separate assessment. Keep evidence of the conditions you confirm.
In what order should you prepare a cash gift to a child?
Four steps avoid most tax reassessments and duty paid by mistake, from checking the past to paying online.
Find the gifts of the last 15 years
They use up the €100,000 allowance and fill the first bands of the scale (General Tax Code, article 784).
Check the conditions of the family cash gift
Giver under 80, recipient of age or emancipated, cash given outright: €31,865 more with no duty (article 790 G).
Pay by transfer or cheque
The payment date starts the one-month period to declare the gift; keep proof of that date.
Declare online and pay online
Since 1 January 2026, in the recipient’s Finances publiques online account, under the heading for declaring a gift: the declaration date starts the 15 years of the allowance.
Which allowance applies, depending on your link with the giver?
The allowance depends on the link between giver and recipient and is renewed every 15 years. The €31,865 family cash gift comes on top for descendants and, where the giver has no descendant, for nephews and nieces.
| Recipient | Allowance per giver | Text | Family cash gift on top |
|---|---|---|---|
| Child | €100,000 | CGI, art. 779 I | €31,865 |
| Grandchild | €31,865 | CGI, art. 790 B | €31,865 |
| Great-grandchild | €5,310 | CGI, art. 790 D | €31,865 |
| Spouse or Pacs partner | €80,724 | CGI, art. 790 E and 790 F | No |
| Brother or sister | €15,932 | CGI, art. 779 IV | No |
| Nephew or niece | €7,967 | CGI, art. 779 V | €31,865 if the giver has no descendant |
| Disability meeting the tax conditions | €159,325 extra | CGI, art. 779 II | Depends on the link |
| Unrelated person or relative beyond the fourth degree | None | 60% scale | No |
Between a parent and a child, the scale runs from 5% on the first €8,072 taxable to 45% above €1,805,677 (article 777). Between brothers and sisters it is 35% then 45%; between an uncle or aunt and a nephew or niece, 55%.
Sources: CGI 779 · CGI 790 B ff. · CGI 790 G · CGI 777
What changed for gifts in France in 2025 and 2026?
Two changes directly affect cash gifts, one temporary, the other permanent.
A cash gift to a child, a grandchild or, where the giver has no descendant, a nephew or niece, used by the last day of the sixth month following payment to buy a new or off-plan home, or for eligible energy renovation of the recipient’s own main residence, is exempt up to €100,000 per giver and €300,000 per recipient, for sums paid until 31 December 2026 (General Tax Code, article 790 A bis).
Source: CGI 790 A bis
A gift of cash or other movable property must be declared online, unless exempted; any duty is paid online. Otherwise a surcharge of 0.2% of the duty, at least €60, may apply.
Sources: impots.gouv.fr · Service-public F1265
How is the duty worked out above the allowances?
Each recipient’s taxable share follows a progressive scale. Between parent and child: 5% up to €8,072, 10% up to €12,109, 15% up to €15,932, 20% up to €552,324, then 30%, 40% and 45% above €1,805,677 (General Tax Code, article 777).
In the worked example of service-public.fr, a €200,000 gift from one parent leaves €100,000 taxable after the allowance; the band from €15,933 to €100,000 alone costs €16,813.60. Across all bands, the duty comes to €18,194.35.
Sources: CGI 777 · Service-public F36656
Why do the gifts of the last 15 years count?
The tax office adds to the new gift any gift made by the same person less than 15 years ago: the allowance already used is no longer available, and the amounts already taxed fill the first bands of the scale (General Tax Code, article 784).
A parent who gave €150,000 to a child 10 years ago has used up the €100,000: a new €10,000 gift of shares is taxed at 20%. A cash gift can still use the €31,865 family cash gift, which is never added back (article 790 G).
Does French gift tax apply if you or your children live abroad?
French gift tax covers gifts of any assets, in France or abroad, when the giver has their tax home in France. When the giver lives abroad, assets located in France remain covered; the recipient’s tax residence may also bring foreign assets within scope (General Tax Code, article 750 ter).
It also covers gifts of any assets received by a recipient whose tax home is in France and who has had their French tax home for at least 6 of the 10 years preceding the year of receipt. A tax treaty can change the answer for a given pair of countries: check it before relying on this page.
Source: CGI 750 ter
Hand-to-hand gift or notarised gift: what is the difference?
A hand-to-hand gift (don manuel) is the physical handing over of movable property: cash, a cheque, an object or shares. It needs no notary, but the recipient must declare it (General Tax Code, article 635 A).
A property cannot be given hand to hand: the gift goes through a notarised deed, and the notary completes the registration formalities, according to impots.gouv.fr and service-public.fr.
Sources: CGI 635 A · impots.gouv.fr
What does article 779 of the General Tax Code say about the €100,000 allowance?
Paragraph I sets the allowance between parents and children, which applies to lifetime gifts and to inheritance alike.
Pour la perception des droits de mutation à titre gratuit, il est effectué un abattement de 100 000 € sur la part de chacun des ascendants et sur la part de chacun des enfants vivants ou représentés par suite de prédécès ou de renonciation.
In English, briefly (our summary, not an official translation): For gift and inheritance duty, €100,000 is deducted from the share of each parent and of each living child, or of a child represented after dying first or renouncing. The allowance applies per giver and per recipient: two parents can each give €100,000 to each of their children. Its renewal every 15 years comes from article 784.
What do people ask before making the transfer?
Do I need a notary to give money to my child in France?
No. According to service-public.fr, a notary is not required for a gift of money. It is required to give a property, and it can help to organise a gift shared between several children (donation-partage).
When and how is a cash gift declared?
Online, in the recipient’s Finances publiques account. For a family cash gift, the declaration must be made within a month of the gift (article 790 G). For a hand-to-hand gift above €15,000, an option lets the duty be paid on the giver’s death (form 2734).
Can the €100,000 and the €31,865 be combined?
Yes. The family cash gift exemption adds to the parent and child allowance (article 790 G). An adult child can receive up to €131,865 free of duty from each parent under 80.
What happens if the giver dies within 15 years?
Gifts of less than 15 years are added back in the estate: the €100,000 allowance already used cannot be used a second time (article 784). Family cash gifts under article 790 G are not added back. Under civil law, the gift also counts towards the children’s reserved share.
Is a gift to buy a home exempt in 2026?
Subject to conditions, for sums paid until 31 December 2026: €100,000 per giver and €300,000 per recipient. Use the money by the last day of the sixth month following payment. A new or off-plan purchase must remain the recipient’s main residence or be let as a main residence for 5 years from acquisition or completion if later; the tenant cannot belong to their tax household. For work eligible for MaPrimeRénov’, the recipient must own the home and keep it as their own main residence for 5 years after completion. The same expenditure cannot combine this exemption with MaPrimeRénov’, the home-employment tax credit or a deduction of expenses (article 790 A bis).
Which texts set the French gift allowances and duty?
- General Tax Code, article 779 (allowances for children, disability, siblings, nephews)Légifrance, in French
- General Tax Code, articles 790 B, 790 D, 790 E and 790 F (grandchildren, great-grandchildren, spouses, Pacs)Légifrance, in French
- General Tax Code, article 790 G (family gift of cash)Légifrance, in French
- General Tax Code, article 777 (scale of gift and inheritance duty)Légifrance, in French
- General Tax Code, article 784 (gifts of less than 15 years added back)Légifrance, in French
- General Tax Code, article 790 A bis (gifts for a new home or energy renovation, until 31 December 2026)Légifrance, in French
- General Tax Code, articles 635 A and 757 (declaring a hand-to-hand gift)Légifrance, in French
- Hand-to-hand gift: online declaration required since 1 January 2026Direction générale des Finances publiques, impots.gouv.fr, in French
- Tax steps for a hand-to-hand gift (fiche F1265)Service-public.fr, in French
- Gift duty: gift of a sum of money (fiche F36656)Service-public.fr, in French
- General Tax Code, article 750 ter (which gifts fall under French duty)Légifrance, in French
Texts cited last checked: 24 September 2026