The statement of sumsStatement · Foreign accounts
Form 3916 in France: the foreign accounts to declare, the fines per account and per year, and a statement of your regularisation
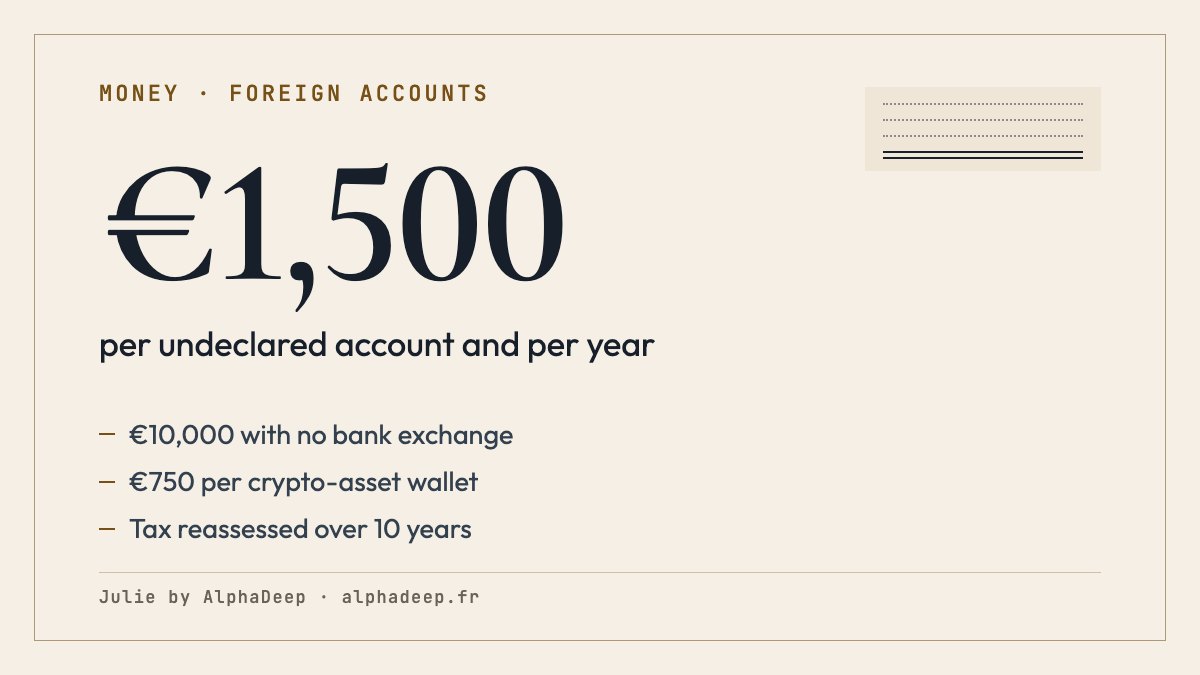
If you live in France, you declare every year, with your income, any account opened, held, used or closed abroad, on form 3916 (General Tax Code, article 1649 A), and your crypto-asset wallets with a foreign provider. Forgetting costs €1,500 per account and per year, €10,000 in a country with no exchange of bank information, and €750 per crypto-asset wallet.
Go to the tool: the statement of sums
Julie by AlphaDeep is an AI legal assistant for French law: it researches official references to help answer your questions (Légifrance, case law, service-public), analyses your documents and drafts your letters, for individuals and professionals alike.
General legal information with official references and dated checks. It is not personalised advice: for a decision that commits you, have your situation checked by a qualified professional.

Let’s look at your situation
Give the accounts and wallets concerned, their country, the years and the highest balances.
Example questions
Your question carries over after signup. Maximum 400 characters. Avoid health data and names.
Which accounts must you declare?
Any account opened, held, used or closed abroad during the year by you or a member of your household, even dormant or with a mere power of attorney: online bank, payment account, crypto-assets, life insurance (CGI article 1649 A; sheet F34342).
For an online bank, look at the IBAN: if it does not start with FR, the account is foreign and is declared every year (sheet F34342).
Sources: CGI, art. 1649 A · Service-public F34342 · CGI, ann. III, art. 344 A
Which exception applies to an online payment account?
No declaration for an account that meets 3 conditions: it is used to pay for online purchases or collect sales of goods, it is linked to an account in France, and the sales collected do not exceed €10,000 in the year (sheet F34342).
If one condition is missing, form 3916 is due for that account.
Source: Service-public F34342
What do you risk, and until when?
A fine of €1,500 per account and per year, €10,000 if the country has no assistance agreement giving access to bank information; for crypto-assets, €750 per wallet, €1,500 above €50,000 (CGI article 1736).
The fine lapses at the end of the fourth year after the offence (Tax Procedures Code, article L188); tax linked to a bank account can be reassessed for 10 years, unless proof establishes total credit balances never exceeded €50,000 during the year when filing was due (article L169). Historical application for crypto-assets needs separate review.
Sources: CGI, art. 1736 · LPF, art. L188 · LPF, art. L169
How much do you risk for the years not declared?
Give the number of accounts and wallets left out, the income years concerned and the balances: the statement works out the fine year by year and dates when it lapses and how long tax can be reassessed. The example: a bank account in an EU country and a small crypto-asset wallet, left out for 2023 and 2024 income.
Fictional example · the fines statement
€4,500.00 of fines at most, if no tax is reassessed; the oldest lapses on 31 December 2028.
- Fine per year not declared
- €2,250.00
- Tax reassessment, latest income
- until 31 December 2034
- Reassessment period
- 10 years, for the income linked to the accounts only
- Income for 2023fine lapses on 31 December 2028, unless interrupted€2,250.00€2,250.00
- Income for 2024fine lapses on 31 December 2029, unless interrupted€2,250.00€4,500.00
Total fixed fines€4,500.00
Time limits read as of 28 September 2026; income years 2021 to 2025. Check the filing year and any interruption for a current application. Calculation limited to accounts with foreign providers, excluding NFTs and direct custody. For 2021 crypto income, the temporal scope of the extended period needs review. Indicative result: if tax is reassessed, the 80% surcharge replaces the fine, and cannot be lower than it.
Which penalties apply to an undeclared account?
Fixed fines per account and per year, replaced by a surcharge if tax is reassessed.
| Failure | Penalty | Text |
|---|---|---|
| Undeclared bank or payment account | €1,500 per account and per year | Article 1736, IV, 2 |
| Account in a country with no access to bank information | €10,000 per account and per year | Article 1736, IV, 2 |
| Undeclared crypto-asset wallet | €750 per wallet or unique crypto-asset | Article 1736, X |
| Wallet worth more than €50,000 in the year | €1,500 | Article 1736, X |
| Omission or error on a wallet | €125, or €250 above €50,000, within a limit of €10,000 per return | Article 1736, X |
| Tax reassessed on the sums in the account | 80% surcharge, which replaces the fine | Article 1729-0 A |
| Sums moved through an undeclared account | Presumed taxable income, unless proven otherwise | Article 1649 A |
| Period to reassess tax | 10 years for linked income; bank exception ≤ €50,000 in filing year; crypto temporal scope to check | LPF article L169 |
The 80% surcharge cannot be lower than the fine it replaces (article 1729-0 A).
Sources: CGI, art. 1736 · CGI, art. 1729-0 A · CGI, art. 1649 A · LPF, art. L169
What does article 1649 A of the French General Tax Code say?
The duty to declare foreign accounts, and the presumption that comes with it.
Les personnes physiques, les associations, les sociétés n’ayant pas la forme commerciale, domiciliées ou établies en France, sont tenues de déclarer, en même temps que leur déclaration de revenus ou de résultats, les références des comptes ouverts, détenus, utilisés ou clos à l’étranger. Les modalités d’application du présent alinéa sont fixées par décret (2).
Les sommes, titres ou valeurs transférés à l’étranger ou en provenance de l’étranger par l’intermédiaire de comptes non déclarés dans les conditions prévues au deuxième alinéa constituent, sauf preuve contraire, des revenus imposables.
In English, briefly (our summary, not an official translation): Individuals, associations and non-commercial companies domiciled or established in France must declare, together with their income or profit return, the references of accounts opened, held, used or closed abroad. The implementing rules are set by decree. Sums, securities or assets moved abroad or from abroad through accounts not declared under the second paragraph are, unless proven otherwise, taxable income. Our note: crypto-asset wallets with a foreign provider fall under a similar duty (article 1649 bis C).
What do French residents with an account outside France ask?
Must a closed account be declared?
Yes, in the year it was closed: the return covers accounts opened, held, used or closed during the year (article 1649 A).
Must an account under a power of attorney be declared?
Yes: a person holding a power of attorney who can use the account must also declare it (sheet F34342).
Are French nationals living in Monaco concerned?
Yes: French nationals whose habitual residence is in Monaco also declare their foreign accounts (sheet F34342).
Does coming forward wipe out the fine?
Article 1736 provides no automatic waiver of these fines: file the missing forms and declare the omitted income before any audit.
Which texts does declaring foreign accounts rest on?
- General Tax Code, article 1649 A (foreign accounts)Légifrance
- General Tax Code, article 1649 bis C (crypto-asset wallets)Légifrance
- General Tax Code, article 1736 (fines)Légifrance
- Tax Procedures Code (Livre des procédures fiscales), article L169, reassessment periodLégifrance
- Tax Procedures Code (Livre des procédures fiscales), article L188, fines lapsingLégifrance
- Must accounts opened abroad be declared? (sheet F34342, in French)Service-public.fr · checked on 9 July 2026
- General Tax Code, annex III, article 344 A (accounts to declare)Légifrance
- General Tax Code, article 1729-0 A (80% surcharge)Légifrance
Texts cited last checked: 27 September 2026