The gaugeIncome tax · work expenses
Actual expenses or the 10% deduction in France: comparing both on your salary, with the mileage scale and meals
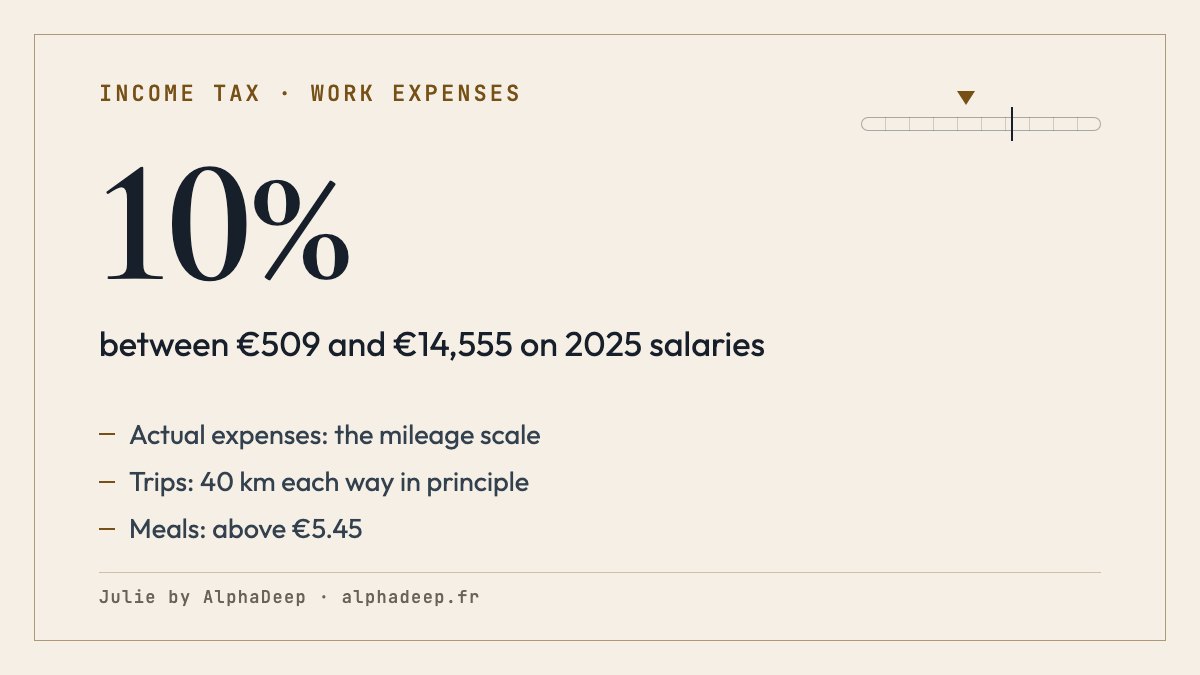
On 2025 salaries declared in 2026, a 10% deduction applies automatically, between €509 and €14,555 per household member (article 83 of the CGI, the General Tax Code). Each person can replace it with actual expenses (frais réels) on proof: trips at the mileage scale, up to 40 km each way unless particular circumstances apply, meals away from home above €5.45. Employer allowances for those costs are then added to taxable salary.
Julie by AlphaDeep is an AI legal assistant for French law: it researches official references to help answer your questions (Légifrance, case law, service-public), analyses your documents and drafts your letters, for individuals and professionals alike.
General legal information with official references and dated checks. It is not personalised advice: for a decision that commits you, have your situation checked by a qualified professional.

Let’s look at your situation
Give your net taxable salary, your trips, your meals and what your employer reimburses.
Example questions
Your question carries over after signup. Maximum 400 characters. Avoid health data and names.
Actual expenses or 10%: which lowers your taxable salary most?
Give your net taxable salary, your trips, your meals and your other expenses: the gauge places your actual expenses, net of employer allowances, against the 10% deduction. The example: €32,000 of salary, 25 km each way for 210 days in a 5 CV car, 210 meals without receipts.
Fictional example · actual-expenses gauge
Actual expenses are better: €6,288.00 against a €3,200.00 10% deduction, so €3,088.00 more to deduct.
- 10% deduction
- €3,200.00
- Trips at the scale, 10,500 km
- €5,143.50
- Meals
- €1,144.50
- Employer allowances to add back
- €0.00
- Net actual expenses
- €6,288.00
- €3,20010% deduction
2025 salaries declared in 2026. Expenses count if paid in the year and justified; the tax saved then depends on your marginal rate.
How is the 10% deduction worked out?
The flat deduction is 10% of salary net of contributions and applies automatically. For pay received in 2025, it cannot be less than €509, without exceeding the salary, or more than €14,555 (article 83, 3°, of the General Tax Code).
It is worked out separately for each member of the tax household, and each can give it up for actual expenses without the other having to do the same (service-public fiche F1989).
Sources: CGI art. 83 · Service-public F1989
When are actual expenses the better choice?
When your justified work expenses, paid during the year, exceed the 10% deduction once you take off the allowances and reimbursements your employer paid for the same costs: by opting for actual expenses, you must add these sums to your taxable salary, including the benefit of a company car (impots.gouv).
The expenses are detailed, nature and amount, in an appended note; the receipts are not attached, but are kept for 3 years for the tax office (fiche F1989).
Sources: impots.gouv · Service-public F1989
How do you count trips between home and work?
Trips under 40 km are allowed in full; beyond that, the deduction covers the first 40 kilometres, unless particular circumstances, linked in particular to the job, justify the full distance (article 83 of the CGI). A car-sharing passenger’s costs are also allowed on proof.
The car can be valued at the mileage scale, by annual distance and fiscal horsepower, raised by 20% for an electric car; tolls, garage, parking and car-loan interest come on top (article 6 B of annex IV to the CGI).
Sources: CGI art. 83 · CGI ann. IV, art. 6 B
How do you deduct meals eaten at work?
Only the extra cost compared with a meal at home, valued at €5.45 for 2025 income, is deductible, when your hours or the distance keep you from going home. With receipts, it is the price paid minus €5.45; without detailed receipts and with no canteen available, €5.45 per meal (impots.gouv).
If a staff canteen exists on site or nearby, only the proven difference between the price paid and €5.45 counts. The employer-funded share of meal vouchers is taken off in every case.
Source: impots.gouv
Which actual expenses weigh most in the calculation?
The items that most often tip the choice, from the most common to the most specific.
Car trips
At the mileage scale: for 10,500 km a year with a 5 CV car, €5,143.50, before tolls and parking.
Meals away from home
€5.45 per meal without receipts, so €1,144.50 for 210 meals, minus the employer’s share of meal vouchers.
Double residence
The second home and its costs when work forces you to live far from home, for example when each spouse works in a distant town.
Trade union dues
Deductible as actual expenses; they then no longer give the tax credit provided for these dues.
Training and equipment
Expenses needed for the job, paid during the year and justified, that no employer allowance covers.
What is the mileage scale for a car?
The formula depends on fiscal horsepower and on the distance driven in the year, d.
| Fiscal horsepower | Up to 5,000 km | From 5,001 to 20,000 km | Above 20,000 km |
|---|---|---|---|
| 3 CV or less | d × 0.529 | (d × 0.316) + €1,065 | d × 0.370 |
| 4 CV | d × 0.606 | (d × 0.340) + €1,330 | d × 0.407 |
| 5 CV | d × 0.636 | (d × 0.357) + €1,395 | d × 0.427 |
| 6 CV | d × 0.665 | (d × 0.374) + €1,457 | d × 0.447 |
| 7 CV or more | d × 0.697 | (d × 0.394) + €1,515 | d × 0.470 |
Result raised by 20% for an electric car. Toll, garage or parking costs and the interest on the car loan come on top of the scale, on proof (article 83 of the CGI).
Sources: CGI ann. IV, art. 6 B · CGI art. 83
What do employees ask before choosing actual expenses?
Do you attach the receipts to the tax return?
No. Detail the nature and amount of the expenses in an appended note, and keep invoices, restaurant bills and mileage records for 3 years for the tax office (service-public fiche F1989).
Must both members of a couple make the same choice?
No. Each member of the tax household chooses the option that suits them best: one can keep the 10% deduction while the other declares actual expenses (fiche F1989).
Can you deduct more than 40 km each way?
Only if particular circumstances, linked in particular to the job, justify the full distance; otherwise the deduction covers the first 40 kilometres (article 83 of the CGI).
Does the employer’s repayment of your travel pass change the calculation?
Yes, if you opt for actual expenses: the employer’s allowances and reimbursements for the costs you deduct are added to your taxable salary (impots.gouv). With the 10% deduction, they are not.
What does article 83 of the CGI say about the 10% deduction?
The text that sets the flat deduction, its limits, and opens the option for actual expenses.
La déduction à effectuer du chef des frais professionnels est calculée forfaitairement en fonction du revenu brut, après défalcation des cotisations, contributions et intérêts mentionnés aux 1° à 2° ter ; elle est fixée à 10 % du montant de ce revenu. Elle est limitée à 14 555 € pour l’imposition des rémunérations perçues en 2025 […]. Le montant de la déduction forfaitaire pour frais professionnels ne peut être inférieur à 509 €, sans pouvoir excéder le montant brut des traitements et salaires.
In English, briefly (our summary, not an official translation): The deduction for work expenses is worked out as a flat amount of 10% of gross income after the contributions listed; it is capped at €14,555 for pay received in 2025, and it cannot be less than €509, without exceeding the gross amount of salaries. The same article lets salary earners justify their actual expenses instead, and in principle caps home-to-work trips at 40 km.
Which texts is this actual-expenses gauge based on?
- General Tax Code, article 83 (10% deduction, actual expenses, 40 km)Légifrance, in French
- General Tax Code, annex IV, article 6 B (mileage scale)Légifrance, in French
- Meal expenses (Frais de repas)impots.gouv.fr, in French · modified on 7 April 2026
- Are actual expenses more favourable for me?impots.gouv.fr, in French · page read on 25 September 2026
- Work expenses: flat deduction or actual expenses (fiche F1989)Service-public.fr, in French · checked by the publisher on 15 April 2026
- When can you opt for double-residence expenses?impots.gouv.fr, in French · page read on 25 September 2026
Texts cited last checked: 26 September 2026